The financial year is well past its halfway mark, most of the CSR amount is still unspent, and the people responsible are fitting CSR in between their main roles while year-end reporting draws closer. This is usually when a company starts looking for CSR consultants.
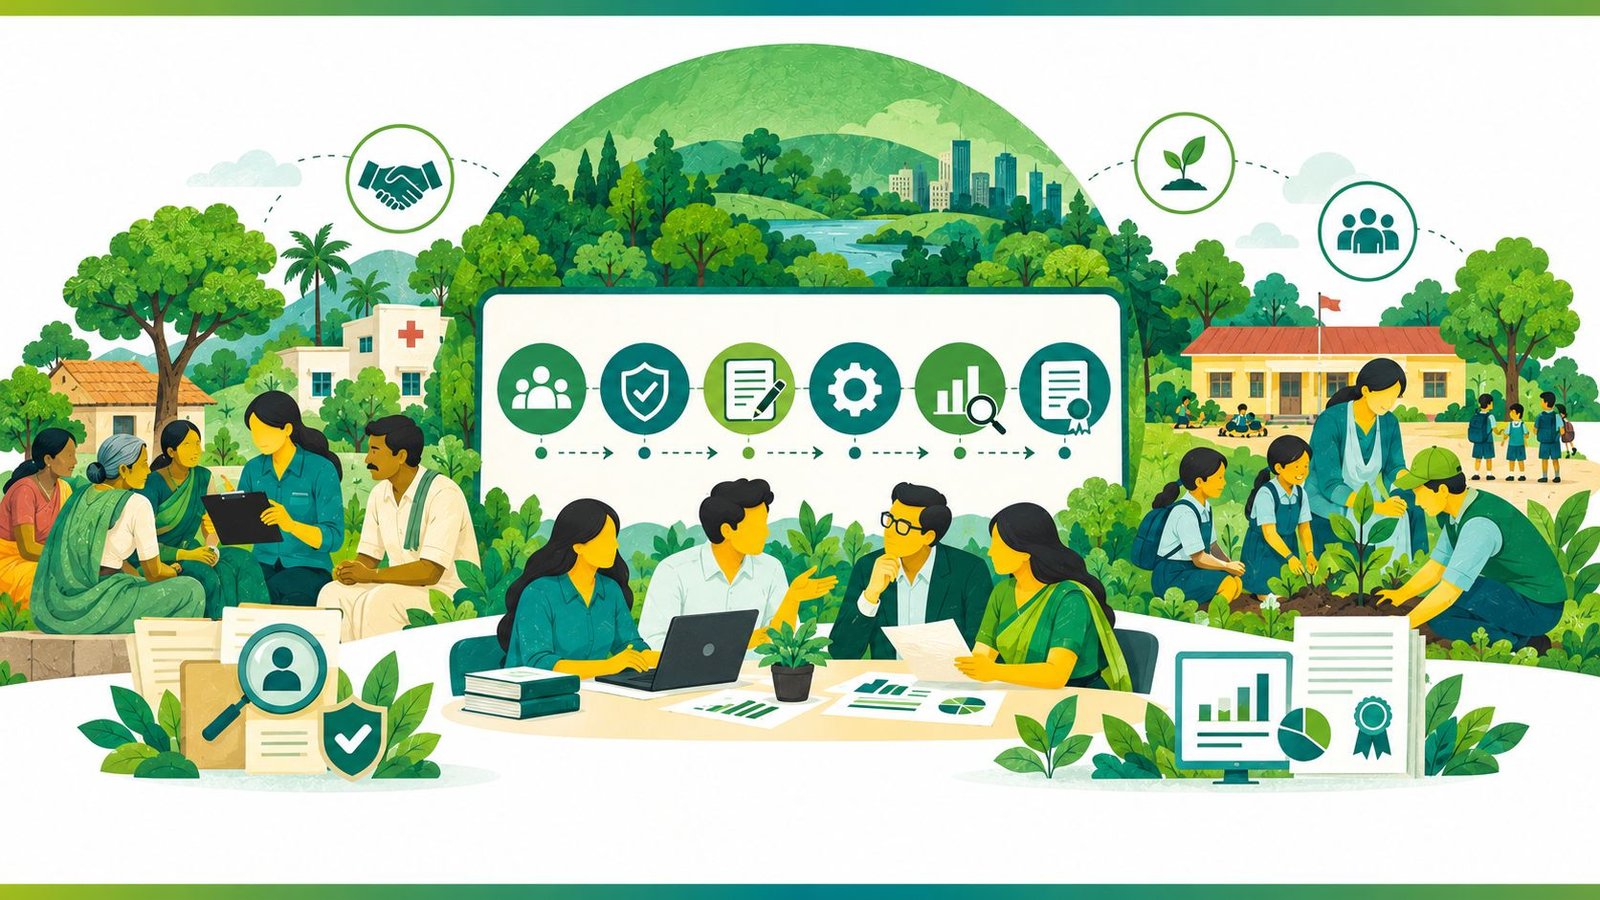
CSR consultants help companies plan, run and report their corporate social responsibility work. They assess community needs, find and check implementing partners, design the programme, support its execution, and monitor and evaluate the results, while the board keeps every decision. A company usually needs one when CSR is handled part-time alongside other roles, when money is left unspent, or when the board wants evidence of change rather than a list of payments.
This guide sets out what a CSR consultant does at each stage, a seven-point check to decide whether your company needs one, how consultants differ from implementing agencies, how consultant fees sit within the CSR rules, and eight questions to ask before you sign.
What does a CSR consultant do?
A CSR consultant covers the full cycle of a CSR programme, from understanding what a community needs to reporting what changed. The board and the CSR Committee still approve every major decision. The consultant does the groundwork that makes those decisions sound.
| Stage | What the consultant does | What the company decides |
|---|---|---|
| 1. Need assessment | Studies the communities around your plants or offices through household surveys, talks with schools, health centres and local government, and a review of existing government schemes. | Which needs to prioritise |
| 2. Implementing partner selection | Shortlists eligible NGOs, checks their CSR-1 registration, track record and accounts, and visits their field work. | Which partner to fund |
| 3. Programme design | Builds the theory of change, indicators, milestones and fund release schedule, and drafts the annual action plan the CSR Committee recommends to the board. | Approval of the annual action plan |
| 4. Execution support | Coordinates with the partner day to day, tracks milestones and links fund releases to progress. | Fund releases and any change in timelines |
| 5. Monitoring and evaluation | Sets a baseline, runs field monitoring visits and measures outcomes at the end. | Course corrections |
| 6. Reporting | Prepares the evidence for the annual report on CSR and the documents needed to certify how the money was used. | Sign-off on the board's report |
Several stages map directly onto the Companies (Corporate Social Responsibility Policy) Rules, 2014, as amended in 2021. Rule 5(2) requires the CSR Committee to recommend an annual action plan covering the approved projects, how they will be executed, the fund utilisation schedule, the monitoring and reporting mechanism, and details of any need and impact assessment. Rule 8(1) requires the board's report to include an annual report on CSR. A corporate social responsibility consultant does the work behind both. Our page on CSR legal requirements covers the wider picture.
Rule 4(5) adds a further check: the board must satisfy itself that disbursed funds were used for the purposes and in the manner it approved, and the Chief Financial Officer, or the person responsible for financial management, must certify this. A certificate is only as strong as the evidence behind it, which is why monitoring visits and partner reporting matter.
Not every engagement covers all six stages. Some companies buy CSR consultancy services for a single stage, such as partner due diligence or CSR monitoring and evaluation, and run the rest in-house. Others hand over the full cycle as a single CSR project management engagement.
When does a company need CSR consultants? A seven-point check
Company size is a weak test. Capacity is a better one. Each statement below describes a gap that CSR consultants are commonly brought in to close.
- CSR is handled part-time by people whose main role is something else.
- Money was left unspent last year, or moved into an Unspent CSR Account for an ongoing project.
- Spending is spread across many one-off donations with no common goal.
- The board or CSR Committee asks what changed on the ground, and there is no data to answer.
- Fund use is certified at year end on the strength of partner invoices alone, without field evidence.
- The company is starting its first multi-year (ongoing) project.
- There is no checked list of implementing partners, or the current partner was chosen through an informal reference.
The second point is worth a closer look. Under Section 135(6) of the Companies Act, 2013, money left unspent on an ongoing project must move to an Unspent CSR Account within thirty days of the end of the financial year and be spent within three financial years. Anything still unspent after that goes to a fund specified in Schedule VII. Unspent money not tied to an ongoing project must go to a Schedule VII fund within six months of the year end, under the proviso to Section 135(5). Either way, it is money the company did not direct to the communities it chose.
CSR consultant, implementing agency or in-house team: who does what?
These three roles are often confused, and the confusion tends to surface at audit time.
An implementing agency runs the programme on the ground. Under Rule 4(1), CSR can be carried out by the company itself or through eligible entities such as Section 8 companies, registered public trusts and registered societies. Rule 4(2) requires these entities to register with the Central Government by filing Form CSR-1, with effect from 1 April 2021.
A CSR consultant sits around both the company and the implementing agency. It does not replace the partner on the ground, and it does not replace the board's decisions. CSR consulting firms design the programme, select and check partners, monitor delivery and turn field data into board-ready reports.
| Role | Main job | Best suited when | Watch out for |
|---|---|---|---|
| In-house CSR team | Owns strategy, approvals and relationships | The company has full-time CSR staff with field and evaluation skills | Overload when CSR is a side responsibility |
| CSR implementing agency | Delivers the programme in the community | Needed unless the company implements directly | A partner chosen without due diligence; weak reporting |
| CSR consultant | Plans, checks, monitors and reports | CSR is run part-time, or the board wants evidence of results | A consultant that also takes fees from the NGOs it recommends |
Most companies that run CSR well use a combination: a named internal owner, one or more checked implementing agencies, and outside support for the stages the internal team cannot cover. Our guide on choosing the right NGO partner for CSR projects covers CSR implementing agency selection in more detail.
How are CSR consultancy services paid for, and can the fee count as CSR spend?
CSR consultancy services are usually priced in one of three ways: a fixed fee for a defined assignment such as a need assessment, a percentage of the CSR amount under CSR project management, or an annual retainer for ongoing advisory support. The right model depends on how much of the cycle you hand over.
Whether the fee can be booked as CSR expenditure depends on what it pays for. Rule 2(1)(b) of the CSR Rules defines administrative overheads as expenses for the general management and administration of CSR functions in the company, and excludes expenses directly incurred for the designing, implementation, monitoring and evaluation of a particular CSR project or programme. Rule 7(1) caps administrative overheads at five percent of total CSR expenditure for the financial year.
This is a reading of the rules as written, not legal or tax advice.
How to choose a CSR consultant: eight questions to ask before you sign
Lists of the top CSR consulting firms in India are easy to find, and corporate social responsibility consulting firms vary widely in what they actually do. A list will not tell you whether a firm suits your company, your districts and your reporting needs. These eight questions will.
- Who will visit the field, and how often? Ask for the people who will do the work, not only those in the pitch meeting.
- How do you run a need assessment? Look for household data, conversations with local institutions and a review of existing government schemes.
- How do you check implementing partners? The answer should cover CSR-1 registration, eligibility under Rule 4(1), audited accounts, past project reports and a field visit.
- Do you receive any fee or commission from the NGOs you recommend? A corporate social responsibility consultant paid by both sides has a conflict of interest. Ask for the answer in writing.
- What evidence will we receive at year end? Expect field-verified evidence of fund use to support the certificate under Rule 4(5), not only partner invoices.
- What will you measure, and from when? Indicators and a baseline should be agreed before the first fund release.
- Who owns the data, and how is beneficiary data protected? Programme data includes personal data of community members. Our guide to the DPDP Act for the social sector explains what that means for CSR programmes.
- What happens at handover? Ask which reports, data and documents stay with the company if the engagement ends.
Looking for CSR consultants in Mumbai, Bangalore, Delhi, Hyderabad, Chennai, Pune or Kolkata? Each city name links to our page for that city.
CSR project management in practice: an illustrative example
This example is a composite, written to show how a CSR project management engagement typically runs. It does not describe a specific company.
A mid-size engineering company with two plants had met its CSR obligation for years through donations to a dozen causes. Board papers were prepared each year, payments were made against invoices, and causes were picked from employee suggestions. When the CSR Committee asked what had changed in the villages near the plants, nobody could say.
April to June: need assessment
The consultant surveyed households in villages around both plants and met school heads, health centre staff and panchayat members. Two needs stood out: girls leaving school after the primary years because the nearest secondary school was far away, and young people without the skills local employers were hiring for.
June to July: partner selection
Six NGOs were screened for CSR-1 registration, eligibility under Rule 4(1), audited accounts and past work. Two were visited in the field, and one was chosen for each need.
July: programme design
The consultant built a theory of change for each programme, agreed indicators and a baseline, and drafted the annual action plan for the CSR Committee, with fund releases tied to milestones.
August to March: execution and monitoring
Monthly reviews with both partners, quarterly field visits and a short dashboard for the CSR Committee. When one partner fell behind on enrolment in the second quarter, the shortfall showed up early and the plan was adjusted with the board's approval.
Year end: reporting
The company received field-verified evidence of fund use to support the certificate under Rule 4(5), inputs for the annual report on CSR, and progress updates and stories, shared with consent, to communicate inside the company.
The board's report that year described two programmes with stated goals and measured progress, in place of a list of payments.
FAQs
Is it mandatory to hire CSR consultants?▾
No. The Companies Act, 2013 does not require a company to hire CSR consultants. The only outside involvement the CSR Rules require is an impact assessment through an independent agency, and only for companies and projects above the thresholds set in Rule 8(3)(a).
What is the difference between a CSR consultant and a CSR implementing agency?▾
An implementing agency delivers the programme in the community and must be an eligible entity under Rule 4(1), registered through Form CSR-1. A CSR consultant plans, checks, monitors and reports on that work for the company.
What is CSR project management?▾
CSR project management is a service in which a consultant manages a company's CSR programme across the full cycle: need assessment, implementing partner selection, programme design, execution support, monitoring and evaluation, and reporting. The board keeps every approval; the consultant does the groundwork and coordination.
Do mid-size companies need CSR consultants, or only large ones?▾
Capacity matters more than size. A mid-size company whose CSR is handled part-time alongside other roles often gains more from outside support than a large company with a full CSR team.
When in the financial year should a company bring in a CSR consultant?▾
Early. Need assessment, partner checks and programme design feed the annual action plan that the CSR Committee recommends to the board under Rule 5(2). Starting early leaves time for proper groundwork and reduces year-end pressure to spend.
The bottom line
The law does not ask a company to hire CSR consultants. It asks the board to spend on approved programmes, to satisfy itself that the money was used as approved, and to report on it. Where the people responsible have the time and skills for that, a company can do it alone. Where CSR is one task among many for the people responsible, outside support is how the work gets done well rather than just done.
About the author. Sudhir Rao is the Founder and Managing Director of Chrysalis Services. An NISM-certified Social Auditor and a member of the CSRBOX Advisory Board, he has led CSR strategy, programme design, and impact assessment engagements across environment, livelihoods, and education sectors. Chrysalis Services has worked across 22+ states and 300+ districts in India.
References
- Companies Act, 2013, Section 135 (Corporate Social Responsibility), as amended.
- Ministry of Corporate Affairs. Companies (Corporate Social Responsibility Policy) Amendment Rules, 2021, G.S.R. 40(E), 22 January 2021. Official PDF